


Denmark Company Formation: A Complete Guide
A practical guide to Denmark company formation, covering ApS and A/S entity types, corporate tax, substance, banking, and who the jurisdiction suits.
This article is more than 24 months old. The rules it describes may have changed since it was published.
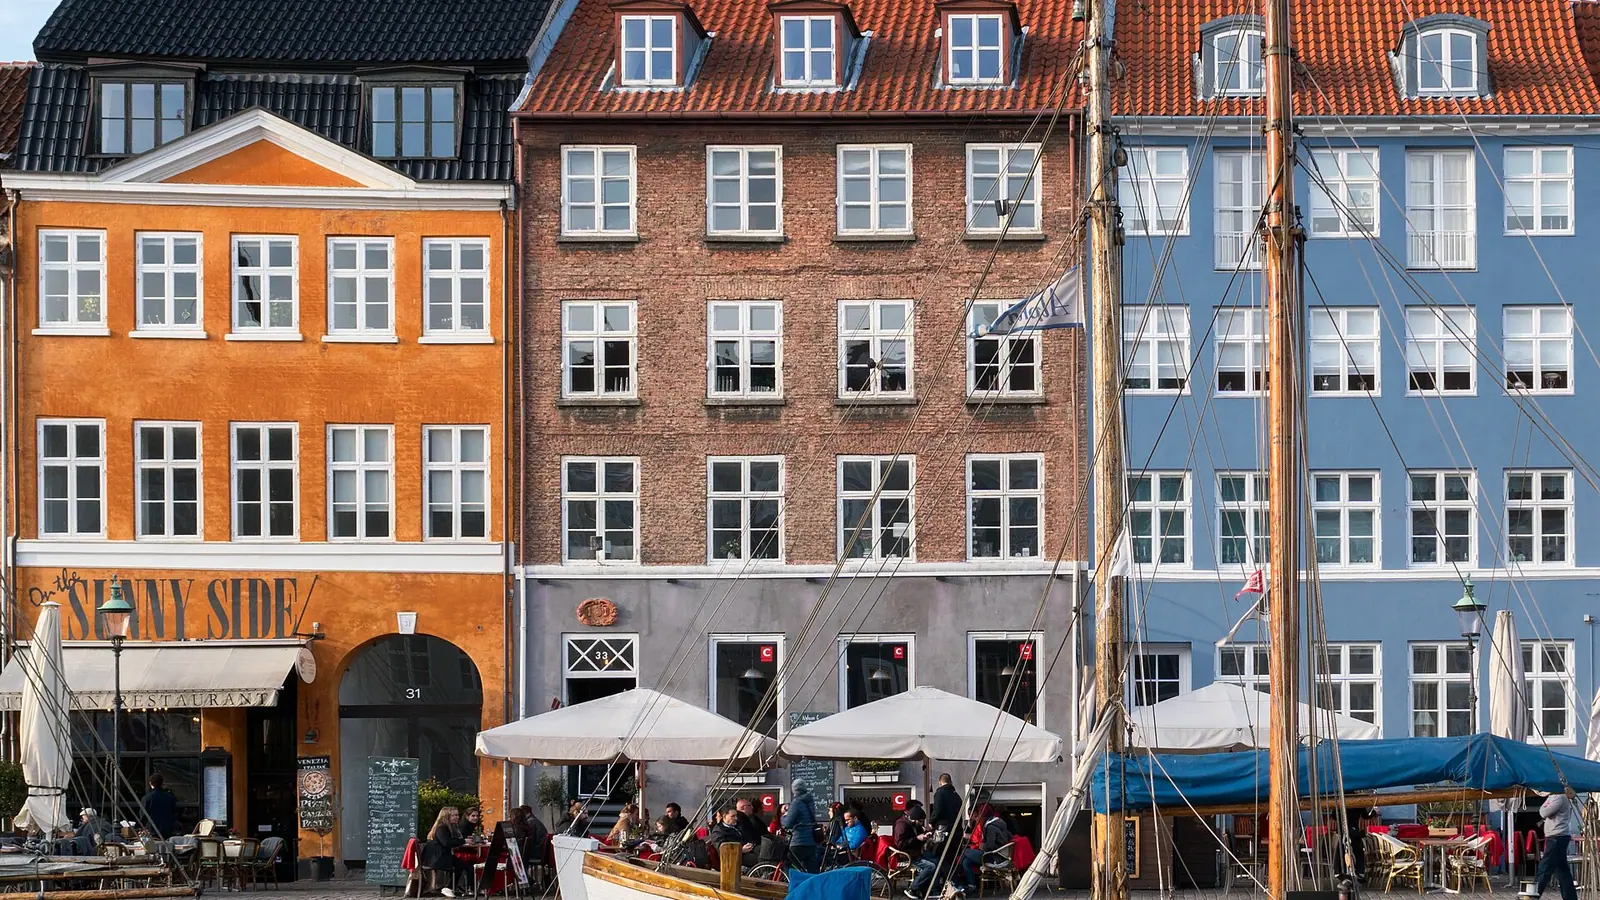
Denmark is rarely the first jurisdiction founders think of when they hear "company formation," and that is precisely why it deserves a closer look. It is not a low-tax haven, and it does not pretend to be. What it offers instead is something many entrepreneurs eventually decide matters more: a transparent, predictable legal system, a genuinely digital public administration, full EU market access, and a reputation that opens doors with banks, investors, and counterparties.
For the right business, Denmark company formation is a route to credibility rather than a route to tax savings. Understanding that distinction up front saves a great deal of disappointment later.
This guide walks through the entity types available, the real tax position, the substance and reporting obligations, the practicalities of banking, and the kind of business for which Denmark genuinely makes sense.
Entity Types and How They Differ
Most international founders incorporating in Denmark choose between two limited-liability forms. The anpartsselskab (ApS), a private limited company, is the workhorse for small and medium businesses. The aktieselskab (A/S), a public limited company, carries higher capital requirements and a more formal governance structure, and is generally chosen by larger groups, regulated businesses, or companies anticipating outside investment or eventual listing.
The ApS requires a modest minimum share capital, while the A/S requires substantially more, with a portion payable on incorporation. Figures are set by statute and have changed over the years, so confirm the current thresholds before committing, as they are periodically revised.
A Danish ApS or A/S is a separate legal person, and shareholders are generally protected from company liabilities beyond their capital contribution. Branches of foreign companies and representative offices are also possible, but they do not create a separate legal entity and expose the parent more directly, so most clients prefer a subsidiary.
There is no general requirement for a Danish-resident director, but board composition and management structure differ between the ApS and A/S, and certain regulated activities impose their own residency or fit-and-proper tests.
The Tax Position
Denmark levies corporate income tax on a company's worldwide profits at a flat national rate that has been stable in recent years. It is a mainstream European rate, neither punitive nor competitive, and you should treat it as a real cost rather than something to be engineered away.
Denmark operates a participation-exemption regime that can exempt qualifying dividends and gains on shares in subsidiaries, which makes it workable as a holding location within a genuinely substantive group. Its extensive treaty network and EU directive access reduce withholding tax friction on cross-border flows, though anti-abuse rules and beneficial-ownership scrutiny are applied with real teeth following the well-known Danish withholding-tax litigation.
VAT applies to most goods and services at the standard Danish rate, with registration obligations once turnover thresholds are met. Payroll taxes and employer obligations are significant where you hire locally, and Denmark's labour and social model should be budgeted for honestly.
Transfer pricing documentation is expected for related-party transactions, and the Danish tax authority is sophisticated. Aggressive structuring tends to be noticed. The sensible posture is commercial substance and clean documentation, not artificial arrangements.
Substance and Governance
Denmark is not a place to park a nameplate company. Tax residence turns on where the company is effectively managed, so a Danish entity controlled entirely from abroad invites questions both in Denmark and in the country where the real decisions are taken.
Where the business has genuine Danish activity, employees, premises, or local management, substance follows naturally. Where it does not, you should think carefully about whether Denmark is the right domicile at all, because the cost base is high and the reporting burden meaningful relative to lighter-touch jurisdictions.
Beneficial ownership must be registered, and Denmark participates fully in international information exchange. This is a transparency-first jurisdiction. For legitimate businesses that is a feature, because the resulting credibility is exactly what attracts serious banks and partners.
Banking and Financial Access
One of Denmark's quiet advantages is that a properly formed and substantive Danish company can usually open banking with established institutions more smoothly than a comparable entity from a flagged offshore centre. Danish and wider Nordic and EU banks recognise the regime and the transparency that sits behind it.
That said, account opening is not automatic. Banks apply rigorous know-your-customer and source-of-funds checks, and a company with no local footprint, non-resident-only directors, and an opaque ownership chain will still face friction. The smoother path is a clear business rationale for being in Denmark, identifiable beneficial owners, and a coherent description of the expected money flows.
For businesses that trade across the EU, the combination of a credible Danish entity and euro or multi-currency banking, alongside the Danish krone, is a practical and durable setup.
Ongoing Compliance
Danish companies must keep proper accounting records and file annual financial statements, which for most entities become publicly available through the business register. Audit obligations depend on size thresholds, and smaller companies may be exempt, though confirm your position as thresholds and exemptions evolve.
Annual corporate tax returns, VAT filings where registered, and payroll reporting where you employ staff are all part of the rhythm. The Danish system is heavily digitised, which makes compliance efficient once you are set up, but the obligations are real and missing them carries penalties.
Because so much is public and digital, Denmark rewards organised operators and is unforgiving of those who treat administration as an afterthought.
Who Denmark Suits
Denmark suits founders and groups that want an unimpeachable EU base: technology and software companies, businesses selling into Scandinavia and the wider EU, holding structures with real substance, and entrepreneurs who value reputation and legal certainty over headline tax efficiency.
It is the wrong choice for anyone seeking a low-tax shell or minimal disclosure. The cost base is high, profits are taxed at a mainstream rate, and almost everything is visible. The pay-off is access, stability, and trust, which for the right business are worth more than a lower tax line.
How HPT Helps
We help clients decide whether Denmark genuinely fits their objectives before any paperwork is filed, then handle incorporation, registration, banking introductions, and the ongoing accounting and compliance calendar through trusted local partners. Where Denmark is part of a wider international structure, we make sure the Danish entity sits sensibly within the whole.
If you are weighing Denmark against other European jurisdictions, speak to us and we will give you a clear, honest view of where it works and where it does not.
This is general information, not advice. It describes rules as we understand them at the date of publication, and those rules differ by jurisdiction and change often. Nothing here takes account of your circumstances, and nothing here creates a professional relationship between us. Advice requires a written engagement letter. Before you act, take advice from a qualified professional in the jurisdiction concerned. Read the full disclaimer.
Talk to us
Does this bear on a matter of yours?
A senior adviser can discuss how it applies to your circumstances.
Sheung Wan, Hong Kong and Mayfair, London · Meetings by appointment only


