


Insights
Notes from the practice
Commentary on cross-border structuring, banking, residence, tax and regulatory change. Articles more than 24 months old carry a note saying so.

All articles
598 articles, page 1 of 13
Asset Protection
Leaving the UK does not end a trust's IHT exposure
A trust's IHT exit charge turns on when the settlor stops being a long-term UK resident and, from 26 November 2025, on later asset switches. Not on day count.
Mobility
Argentina's passport comes with no tax residency, by law
Argentina's US$350,000 passport carries a statutory carve-out from tax residency, but the citizenship process behind it has been challenged in court.
Tax Strategy
Hungary's wealth tax looks through your foreign holdco
Hungary's wealth tax limits non-residents to Hungarian assets, but it reaches through a foreign holding company to the Hungarian property it owns.
Asset Protection
Your trust's law stops at the border of the land it holds
A Nevada trust did not shield California land. The land's law, not the trust's, decided whether a federal judgment creditor could reach it.
Corporate
Mauritius family offices need an entity, not an office
Mauritius's 2026 family office Rules require a corporate applicant and set no office or staff test. Existing licensees must comply after 31 December 2026.
Corporate
US-formed LLCs are exempt from federal BOI reporting
Since FinCEN's August 2026 rule, a US LLC owned from abroad files no federal ownership report. A foreign company registered in a US state still does. Banks still collect the same ownership details, and state and home-country rules still apply.
Fintech
GENIUS Act: no foreign stablecoin issuer has a US route yet
A foreign stablecoin issuer needs Treasury to find its home regime comparable, and no such finding is public. Where an issuer licenses now shapes US access.
Regulatory
Swiss transparency register: foreign holdcos may be in scope
Switzerland's non-public register binds foreign companies that own Swiss land or are run from Switzerland. Most must file by 1 April 2027.
Compliance
Overseas entities register: trust data now one request away
Since 9 July 2026 a single-entity request for trust data needs only the entity's name and ID. Privacy now turns on what was filed and how it was classified.
Tax Strategy
Cyprus non-dom extension: is the €250k fee worth it?
Cyprus's paid non-dom extension costs €250,000 per five years. Set against the new 5% dividend rate, it pays only for founders drawing over €1m a year.
Tax Strategy
FIG regime: the year-five cliff most arrival plans miss
FIG relief ends after four tax years with no taper, and worldwide IHT starts in year eleven. Both dates are fixed on arrival. Most plans model neither.
Structures
China's offshore trust tax: why unwinding now costs more
China's 2026 rules end the offshore trust as a tax deferral, not as a succession tool. A rushed wind-up adds an exit tax and loses the trust.
Mobility
California billionaire tax: the residency date is the risk
Proposition 40 fixes residency at 1 January 2026. Late leavers face a domicile audit, not just the 3 November vote, and offshore trusts do not shield them.
Banking
BVI grey list: redomiciling is the wrong fix for banking
Moving a BVI company to Cayman or Abu Dhabi rarely speeds an EU bank's enhanced due diligence. A complete source-of-wealth and ownership file does.
Comparison
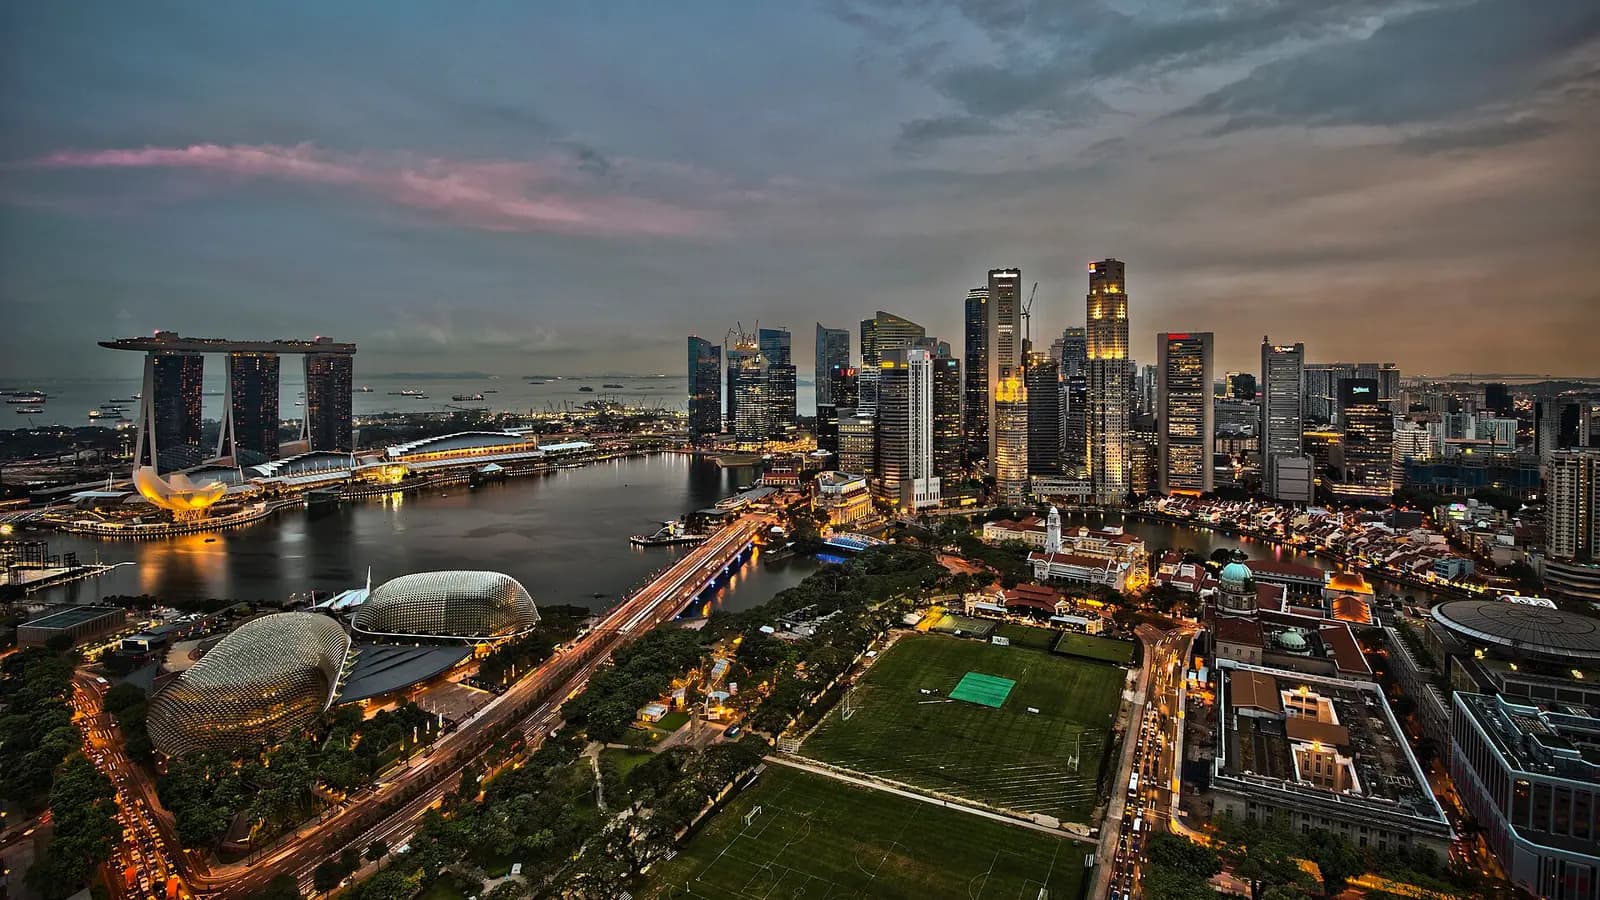
UAE vs Singapore in 2026: Company, Residency and Wealth Compared
A 2026 side-by-side of the UAE and Singapore for company, residency and wealth: tax, substance, banking, treaties, lifestyle and who each suits best.
Tax Strategy
UK Non-Dom Reform 2025: What Really Changed
The UK non-dom reform 2025 abolished domicile-based taxation and moved to a residence test. Here is what actually changed and how to plan around it.
Structures
Trust vs Foundation: Choosing the Right Vehicle for Family Wealth
Trust vs foundation for succession: control, beneficiary rights, legal personality, tax neutrality and cross-border recognition, and which suits which family.
Tax Strategy
Split-Year Treatment: Leaving the UK Cleanly Mid-Year
How split-year treatment works when leaving the UK mid-year, the cases that apply, and the pitfalls that cost departing residents their relief.
Tax Strategy
UK Statutory Residence Test: Complete 2026 Guide
A practical 2026 guide to the UK statutory residence test: automatic overseas and UK tests, the sufficient ties test, day counting, and common traps.
Regulatory
HMRC Connect: How Offshore Assets Are Tracked
How HMRC Connect and global data exchange let the UK tax authority track offshore assets, and what compliant taxpayers should understand about disclosure.
Tax Strategy
Remittance Basis for Non-Domiciled UK Residents
A practical guide to the remittance basis for non-domiciled UK residents: how it works, what counts as a remittance, costs, and the reforms reshaping it.
Tax Strategy
UK Inheritance Tax and Offshore Assets in 2025
How UK inheritance tax now reaches offshore assets in 2025, the move to residence-based scope, excluded property, and planning for international families.
Tax Strategy
Business Asset Disposal Relief: A Founder's BADR Guide
A clear guide to Business Asset Disposal Relief (BADR): who qualifies, the lifetime limit, the rising rate, and how founders should plan an exit.
Tax Strategy
Germany Exit Tax (Wegzugsteuer): A Planning Guide
How Germany's exit tax (Wegzugsteuer) taxes unrealised gains on company shares when you leave, who it catches, and how to plan a departure properly.
Tax Strategy
UK Exit Tax? Capital Gains on Leaving the UK
Does the UK have an exit tax on capital gains when you leave? We explain the temporary non-residence rule, what is taxed on departure, and timing of disposals.
Tax Strategy
France Tax Residency: The Four Tests Explained
France decides tax residency using four alternative tests under Article 4B. Understand how home, main stay, economic activity and centre of interests apply.
Mobility
The Citizenship-by-Investment Buyer's Guide for 2026
How to compare citizenship-by-investment programmes in 2026 on visa-free access, true all-in cost, family inclusion, due diligence and tax position.
Tax Strategy
Andorra Tax Residency: A Practical Relocation Guide
How to obtain Andorra tax residency: the active and passive routes, presence and investment requirements, the low-tax regime, and the pitfalls to avoid.
Tax Strategy
Scotland LBTT and Offshore Property Buyers: A Guide
How Scotland's Land and Buildings Transaction Tax applies to offshore and non-resident buyers, including the ADS surcharge, ownership structures and pitfalls.
Tax Strategy
Portugal's NHR Replacement in 2026: What Changed
Portugal's NHR regime closed to new entrants. Here is what replaced it, who the IFICI incentive suits in 2026, and how it compares for professionals.
Tax Strategy
UK Crypto Tax 2026: A Guide for Wealthy Individuals
How UK crypto tax works for individuals in 2026: capital gains versus income, disposals, DeFi and staking, record-keeping and HMRC's focus.
Tax Strategy
Italy's Flat Tax Regime for New Residents: A Guide
How Italy's flat tax regime for new residents works in 2026: the annual substitute charge on foreign income, who qualifies, and the key pitfalls.
Tax Strategy
Italy's Flat-Tax Regime for New Residents Explained
How Italy's flat-tax regime for new residents works in 2026: the annual substitute tax on foreign income, eligibility, family extension and duration.
Tax Strategy
Greece Flat Tax Regime: A Guide for Foreign Investors
How the Greece flat tax regime works for non-domiciled investors, pensioners and professionals relocating to Greece, with eligibility, costs and pitfalls.
Tax Strategy
Switzerland Lump-Sum Taxation: A Complete Guide
How Switzerland lump-sum taxation (forfait) works for wealthy foreigners: eligibility, how the base is calculated, cantonal differences and key pitfalls.
Regulatory
EMI, PSP, VASP or MSB: A Fintech Licensing Decision Framework
A decision framework for choosing between EMI, PSP, VASP and MSB licences: what each permits, capital and substance, jurisdictions, timelines and banking.
Regulatory
BEPS Pillar Two: The Global Minimum Tax Explained
A clear guide to BEPS Pillar Two and the 15% global minimum tax: who is in scope, how the GloBE rules work, and what it means for offshore structures.
Mobility
Cheapest Citizenship by Investment in 2026: Honest Guide
An honest look at the cheapest citizenship by investment routes in 2026 and what the lower-cost Caribbean programmes really cost once fees are added.
Regulatory
OECD Pillar One: How Profit Reallocation Will Work
OECD Pillar One reallocates taxing rights over the largest multinationals to market jurisdictions. Here is what it means and who it affects.
Regulatory
Pillar Two First-Year Compliance: What to Do Now
Pillar Two compliance in its first year is a data and process challenge. Here is a practical guide to GloBE calculations, safe harbours, and filings.
Regulatory
FATCA for Individuals: Your Reporting Obligations
FATCA for individuals means US persons must report foreign financial assets on Form 8938. Here is who is affected and how it differs from the FBAR.
Regulatory
FBAR Reporting Requirements for US Persons Explained
FBAR reporting requirements catch many US persons with foreign accounts. Here is who must file FinCEN Form 114, what counts, and the penalties.
Regulatory
Transfer Pricing Essentials for Multinational Groups
Transfer pricing essentials for multinationals: the arm's length principle, documentation, methods, and how to manage audit risk across borders.
Mobility
Fastest Second Passport in 2026: What's Realistic
Which routes deliver the fastest second passport in 2026, what really drives processing times, and how to set realistic expectations.
Regulatory
Transfer Pricing Basics Every Entrepreneur Should Know
Transfer pricing basics for entrepreneurs: when the rules apply to your group, the arm's length principle, simple documentation, and pitfalls to avoid.
Regulatory
Permanent Establishment Risk in the Remote-Work Era
Permanent establishment risk from remote work: how home-based employees and roaming founders can create a taxable presence abroad, and how to manage it.
Deals
A Pre-Sale Structuring Playbook for Founders 12-24 Months From Exit
How founders should structure holding entities, residency, reliefs and trusts in the 12-24 months before a liquidity event, and the costly mistakes to avoid.


Also in Insights
Reference

Guides and comparisons
Longer guides on jurisdictions, structures and routes to residence.
Find out more
Example scenarios
Illustrative scenarios showing how a matter is approached.
Find out more
Glossary
Plain-English definitions of cross-border terms, from ATED to VASP.
Find out more
Questions clients ask
How the firm works, what it charges and where it operates.
Find out moreNewsletter
The adviser's note
A quarterly note on banking, structures, residence and regulatory change. No marketing emails.
Unsubscribe at any time. We do not share email addresses. See the privacy policy.
What it covers
Much of the firm's thinking sits in client memoranda rather than published articles. The note covers the parts that apply more widely: changes in jurisdictions, banking practice and regulatory deadlines.

Next step
Tell us about your matter.
A short application tells us what you need. We aim to reply within 48 hours. If we are not the right firm, we will say so.