Guernsey Insurance-Linked Securities (ILS): A Guide
How Guernsey structures insurance-linked securities (ILS): cells, transformers, the regulatory route, tax position and where the jurisdiction adds value.
Insurance-linked securities exist because capital markets can absorb risks that traditional reinsurance balance sheets find hard to hold. Catastrophe exposure, mortality risk and other low-correlation perils can be packaged into instruments that investors buy for yield and diversification. The challenge is building a vehicle that is bankruptcy-remote, regulator-approved and capable of moving capital efficiently between cedants and investors.
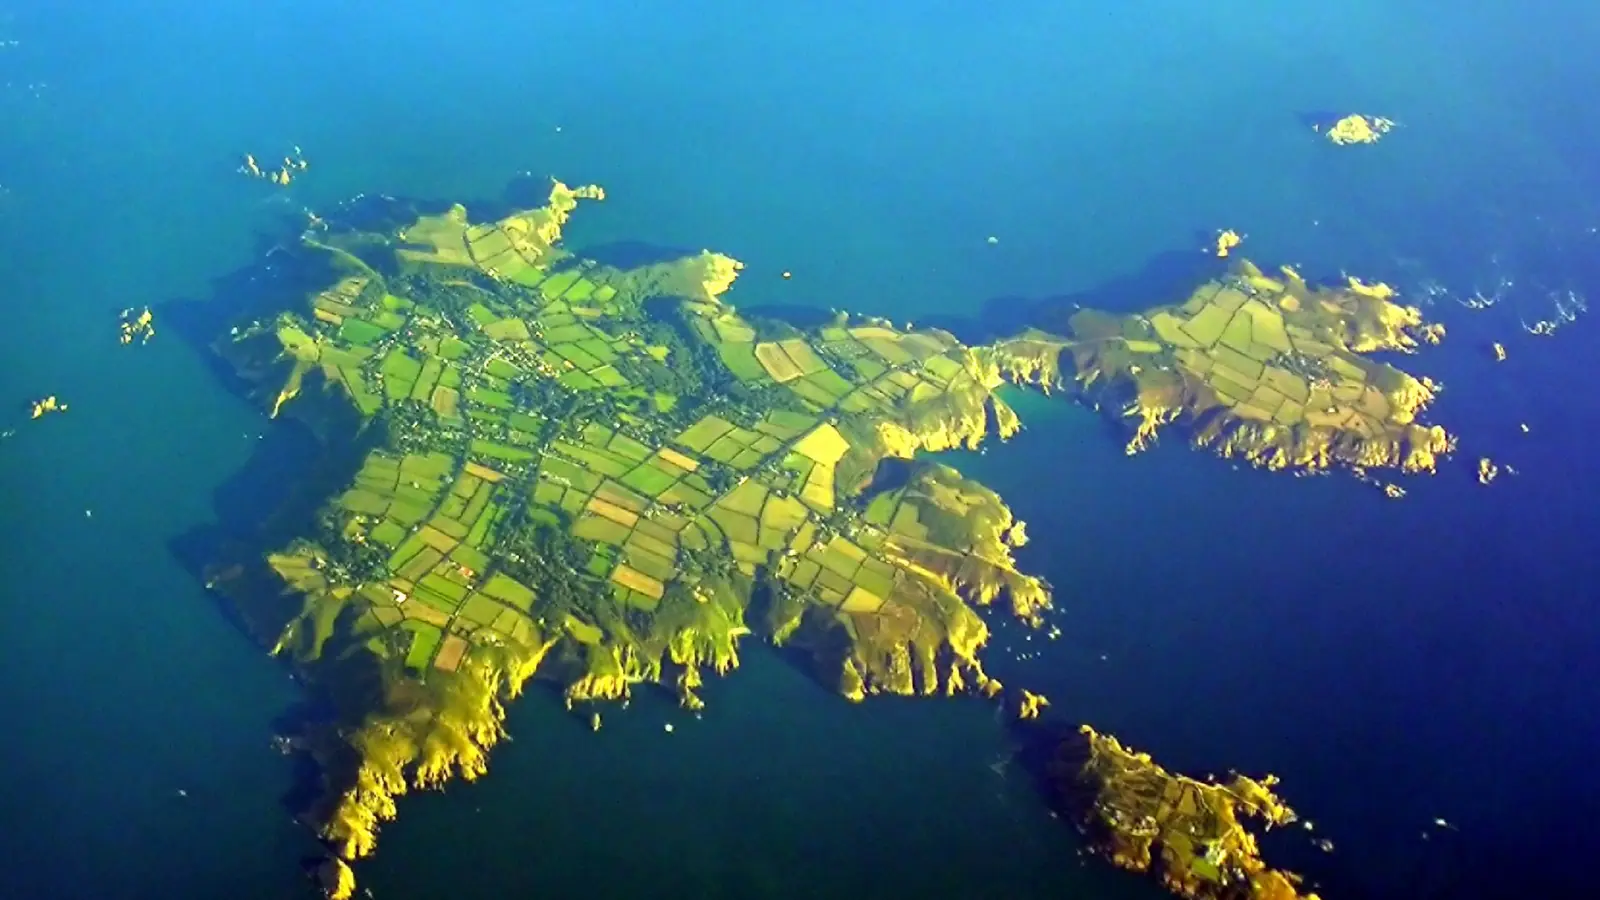
Guernsey has been doing exactly this for years and is widely regarded as one of the leading domiciles for insurance-linked securities. Its cell-company legislation, experienced regulator and deep bench of managers and administrators make it a natural home for ILS transactions. This guide explains how those structures work on the island and where the jurisdiction genuinely adds value.
Why Guernsey for ILS
The island pioneered the protected cell company (PCC) and later the incorporated cell company (ICC), the legal building blocks on which much of the global ILS market now relies. A cell structure lets a single platform house many separate transactions, each ring-fenced from the others, without standing up a new standalone insurer for every deal.
Beyond the law, Guernsey offers a pragmatic regulator in the Guernsey Financial Services Commission, a concentration of specialist insurance managers, and a track record that gives cedants and investors confidence. For sponsors who want to issue repeatedly, the ability to add cells to an existing platform is a meaningful cost and speed advantage.
The core structures
The protected cell company is the workhorse. A single legal entity creates individual cells, each with its own assets and liabilities legally segregated from the core and from every other cell. A catastrophe bond, a collateralised reinsurance arrangement or a sidecar can each sit in its own cell, so that a loss in one transaction does not reach the capital supporting another.
The incorporated cell company goes a step further by giving each cell its own separate legal personality. That distinction matters where counterparties want the comfort of contracting with a discrete legal entity, or where a cell may need to be sold or wound down independently.
The transformer concept underpins most ILS deals. The cell typically writes a reinsurance contract with the cedant and simultaneously issues notes or takes in collateral from investors, transforming insurance risk into an investable security. The cell is fully collateralised, so its obligations to the cedant are backed by assets held in trust or in a controlled account rather than by an open-ended balance sheet.
Sidecars, collateralised reinsurance vehicles and catastrophe-bond issuers can all be built on these foundations, and the same platform can support several at once.
The choice between a standalone vehicle and a cell on a shared platform is mainly one of cost, repeatability and counterparty preference. A sponsor expecting a single, large, long-dated transaction may prefer a dedicated entity, while a programme of recurring annual issuance usually favours a cell platform that can be added to without rebuilding the legal and operational infrastructure each time.
The regulatory route
ILS vehicles in Guernsey are licensed insurers and are supervised accordingly, but the regime is calibrated to the fully collateralised, sophisticated-investor nature of the business. The GFSC has developed proportionate routes for special-purpose insurers and has, at times, offered expedited consideration for transactions that fit established templates and use experienced local managers.
We would stress that any expedited treatment depends on a clean, complete application and a recognised structure. Novel features, unusual collateral arrangements or unfamiliar counterparties will rightly attract more scrutiny. An experienced Guernsey insurance manager is effectively mandatory in practice, both to run the cell and to navigate the licensing conversation with the regulator.
Solvency, governance and reporting obligations apply, scaled to the fact that the vehicle is collateralised and not taking open market risk. Substance expectations, board oversight and proper administration are part of the package and should not be treated as formalities.
It is also worth understanding how the regulatory perimeter interacts with the documentation. The reinsurance contract between cell and cedant, the notes or participation interests issued to investors, and the collateral trust or account agreement must all align so that triggers, payment waterfalls and release conditions are consistent. Where they are not, the protection investors believe they have, or the recovery the cedant expects, can fall short precisely when a loss event puts the structure to the test. The regulator, the cedant and the investors all rely on that internal consistency.
Tax position
Guernsey's tax environment is one of the reasons the island is efficient for ILS. There is no capital gains tax, and the standard rate of company income tax is zero for most activities as at 2026, which generally allows an ILS cell to operate without a domestic tax drag at the vehicle level. Investors are taxed in their own jurisdictions on the returns they receive.
As with any modern cross-border structure, the analysis does not end at the Guernsey border. Withholding tax on flows, the tax characterisation of the instruments in investors' home countries, and the application of CRS and FATCA reporting all need to be considered. Larger sponsor groups should also keep the global minimum-tax framework in view where it applies to them. We always recommend home-jurisdiction advice for both the sponsor and the investor base.
Who ILS suits, and the pitfalls
ILS structures suit reinsurers and large insurers seeking alternative capital, hedge funds and institutional investors seeking uncorrelated returns, and sponsors who expect to issue repeatedly and want a reusable platform. They are not retail products, and they assume sophisticated participants on both sides.
The most common pitfall is underestimating collateral mechanics. The protection investors rely on, and the comfort the cedant takes, both depend on collateral being correctly held, valued and released. Getting the trust or account arrangements and the trigger definitions right is where deals succeed or fail.
A second pitfall is treating the cell platform as set-and-forget. Each cell is a regulated insurance arrangement with its own governance, reporting and solvency obligations, and the platform sponsor remains responsible for the integrity of the whole.
A third is leaving the insurance manager and administrator selection too late. These providers are central to both speed and credibility, and the best of them are involved from the structuring stage.
How HPT helps
We help sponsors and investors evaluate whether Guernsey is the right ILS domicile, choose between PCC and ICC platforms, and assemble the insurance manager, collateral arrangements and banking relationships that make a transaction bankable. We coordinate the regulatory route with the GFSC and the cross-border tax and reporting analysis so that issuance is efficient and defensible.
If you are considering an ILS programme or a single transaction, we would welcome the conversation.
This is general information, not advice. It describes rules as we understand them at the date of publication, and those rules differ by jurisdiction and change often. Nothing here takes account of your circumstances, and nothing here creates a professional relationship between us. Advice requires a written engagement letter. Before you act, take advice from a qualified professional in the jurisdiction concerned. Read the full disclaimer.
Talk to us
Does this bear on a matter of yours?
A senior adviser can discuss how it applies to your circumstances.
Sheung Wan, Hong Kong and Mayfair, London · Meetings by appointment only