


Malta Tax Residency: A Practical Guide
A practical guide to Malta tax residency: ordinary residence, the non-dom remittance basis, the residence programmes, substance, and the pitfalls.
This article is more than 24 months old. The rules it describes may have changed since it was published.
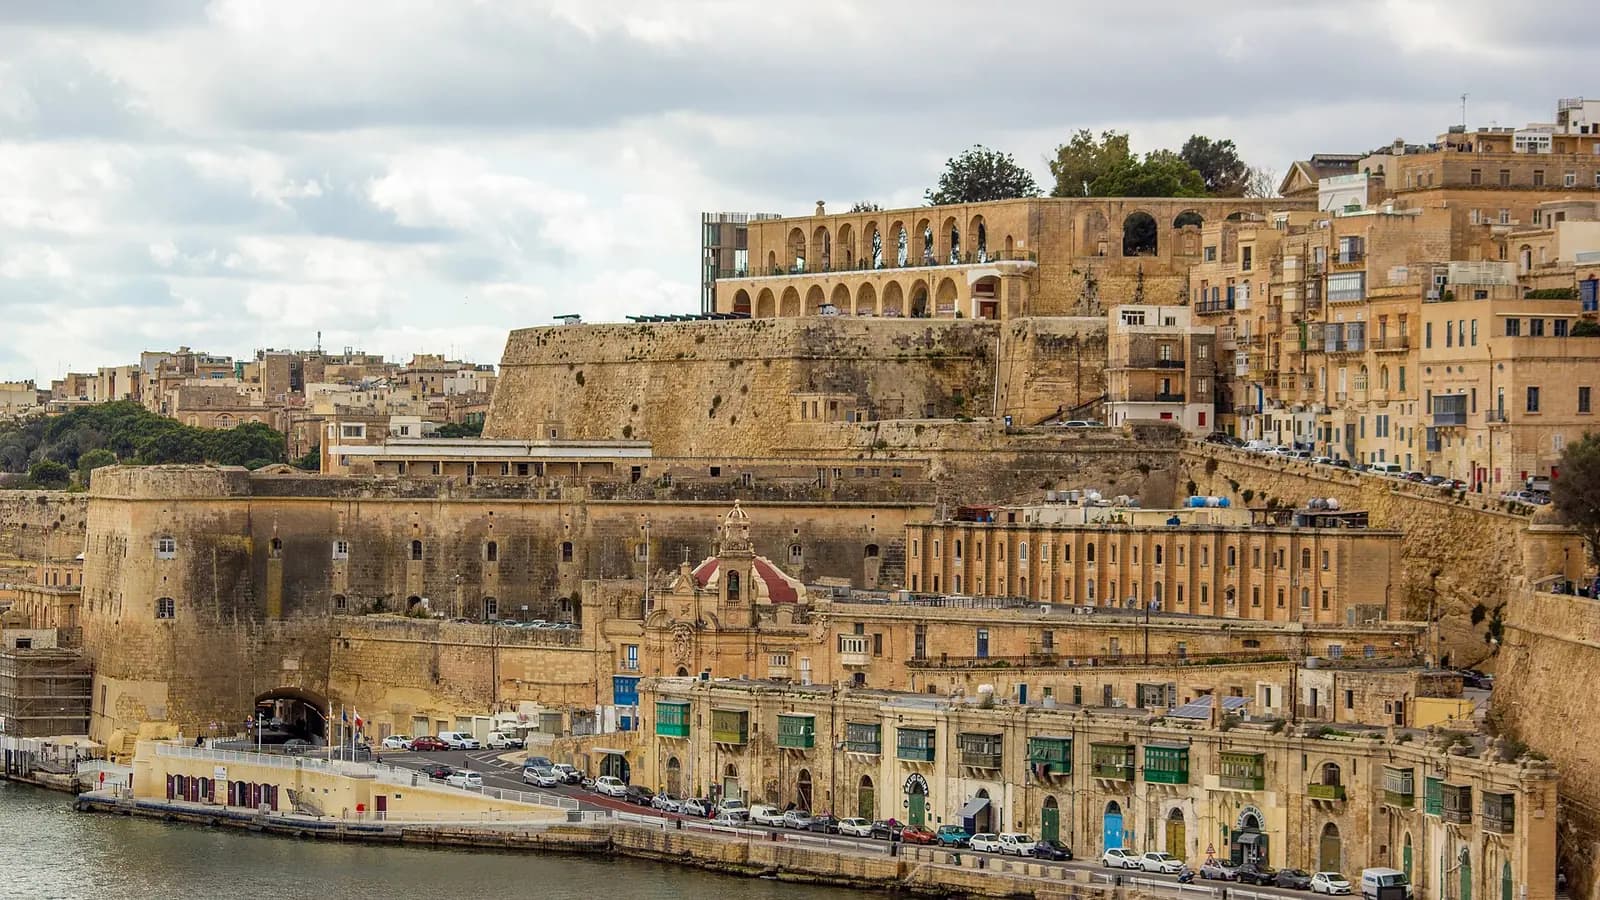
Malta has become a natural base for internationally mobile entrepreneurs, investors and retirees. As an English-speaking EU member with a common-law-influenced legal system and a long tradition of cross-border financial services, it offers a credible European footing without the cost or complexity of larger jurisdictions.
The cornerstone of its appeal is a remittance basis of taxation available to residents who are not domiciled in Malta. Handled correctly, this can mean foreign income is taxed only when brought into Malta, while Maltese-source income is taxed in the ordinary way.
This guide explains how Malta tax residency is established, how residents are actually taxed, the dedicated residence programmes that formalise the position, the substance you need, and the errors we see most often.
How Malta Determines Tax Residency
Malta does not rely on a single rigid day count. Residency is a question of fact, with physical presence of more than 183 days in a calendar year being a strong indicator, but shorter or patterned presence combined with a settled connection to Malta can also create residence.
The concept that matters most is ordinary residence: living in Malta with a degree of continuity and an intention to remain, as opposed to a fleeting visit. Someone who establishes a home, spends substantial time on the island and integrates into life there will generally be ordinarily resident.
Crucially, Malta distinguishes residence from domicile. Most newcomers are resident but non-domiciled, and it is this combination that unlocks the remittance basis. Domicile is a deeper, longer-term concept of permanent home and is not acquired simply by moving to Malta.
The Tax Position for Residents
For an individual who is resident and domiciled in Malta, worldwide income is taxable. For the far more common resident non-domiciled individual, Malta taxes Maltese-source income and capital gains in full, and foreign income only to the extent it is remitted to Malta. Foreign capital gains are generally not taxed even if remitted, which is a meaningful distinction.
Income that is taxed is subject to progressive personal rates. There is a minimum annual tax floor for many non-doms with substantial foreign income, intended to ensure a baseline contribution. The precise figures and conditions are set by statute and can change, so they should be confirmed for the relevant year rather than assumed.
Malta has no annual wealth tax, no inheritance tax and no gift tax in the conventional sense, although duty on documents and transfers can apply to certain assets, notably Maltese real estate and shares. This absence of recurring wealth taxation is part of what draws long-term residents.
The remittance basis demands discipline. To benefit, foreign income must genuinely remain offshore, which usually requires careful separation of capital and income, dedicated accounts, and conscious management of what funds are used to meet Maltese living costs.
Residence Programmes and Routes
Many relocating individuals formalise their position through a dedicated programme rather than relying on ordinary residence alone. Malta offers several, aimed at different audiences, including programmes for EU and EFTA nationals and separate routes for third-country nationals, as well as a long-term residence-by-investment programme.
These programmes typically require a qualifying property, whether purchased or rented above a minimum threshold, evidence of stable resources and health cover, and in some cases a fixed annual minimum tax. In return they confer a clear, special tax status that sits comfortably alongside the non-dom remittance basis.
Selecting the right programme is a function of nationality, family composition, intended time in Malta and long-term goals. A retiree seeking stability has different priorities from a founder who wants EU residence while building a business, and the routes are not interchangeable.
Substance and Practical Living
Malta expects genuine connection. A residence programme application without real presence is exposed both to Maltese scrutiny and to challenge from the country you are leaving. The strongest position combines a real home, meaningful time on the island, local banking, and the relocation of personal and family ties.
Banking deserves particular attention. Malta is an established financial centre, but onboarding standards are now demanding, and applicants should expect thorough source-of-wealth and source-of-funds review. Allowing realistic time for account opening avoids the common situation of holding residence but struggling to operate day to day.
We advise clients to keep clean records of days spent, accommodation, and the structure of their accounts from the outset. The remittance basis in particular lives or dies on documentation.
Common Pitfalls
The most damaging mistake is mixing capital and income in a single account, then remitting from it. Once funds are commingled, demonstrating that a remittance came from clean capital rather than taxable foreign income becomes difficult, and the protective benefit of the remittance basis can be lost.
A second pitfall is assuming residence in Malta automatically ends residence elsewhere. Your former country's own rules, exit charges and tie-breaker tests under any double tax treaty continue to operate, and a half-hearted move can leave you taxed in two places.
Third, some treat a residence programme as the whole answer. The programme confers status, but the remittance discipline, the minimum tax obligations, and ongoing transparency reporting under automatic exchange of information all still require active management.
Finally, do not overlook duty and property rules. Maltese real estate transactions and certain share transfers carry their own charges, and the lifestyle decision to buy property has tax consequences that should be planned, not discovered later.
How HPT Helps
We assess whether Malta genuinely fits your profile, select the appropriate residence route, and structure your banking and account architecture so the non-dom remittance basis is preserved rather than inadvertently forfeited. We coordinate with Maltese advisers and work to make your departure from your former jurisdiction clean and properly documented.
If Malta is on your shortlist, talk to us before you sign a lease or open an account.
This is general information, not advice. It describes rules as we understand them at the date of publication, and those rules differ by jurisdiction and change often. Nothing here takes account of your circumstances, and nothing here creates a professional relationship between us. Advice requires a written engagement letter. Before you act, take advice from a qualified professional in the jurisdiction concerned. Read the full disclaimer.
Talk to us
Does this bear on a matter of yours?
A senior adviser can discuss how it applies to your circumstances.
Sheung Wan, Hong Kong and Mayfair, London · Meetings by appointment only


