


Monaco Company Formation: A Complete Guide
A complete guide to Monaco company formation: entity types, the tax position, substance and residence, banking access, and who the Principality suits.
This article is more than 24 months old. The rules it describes may have changed since it was published.
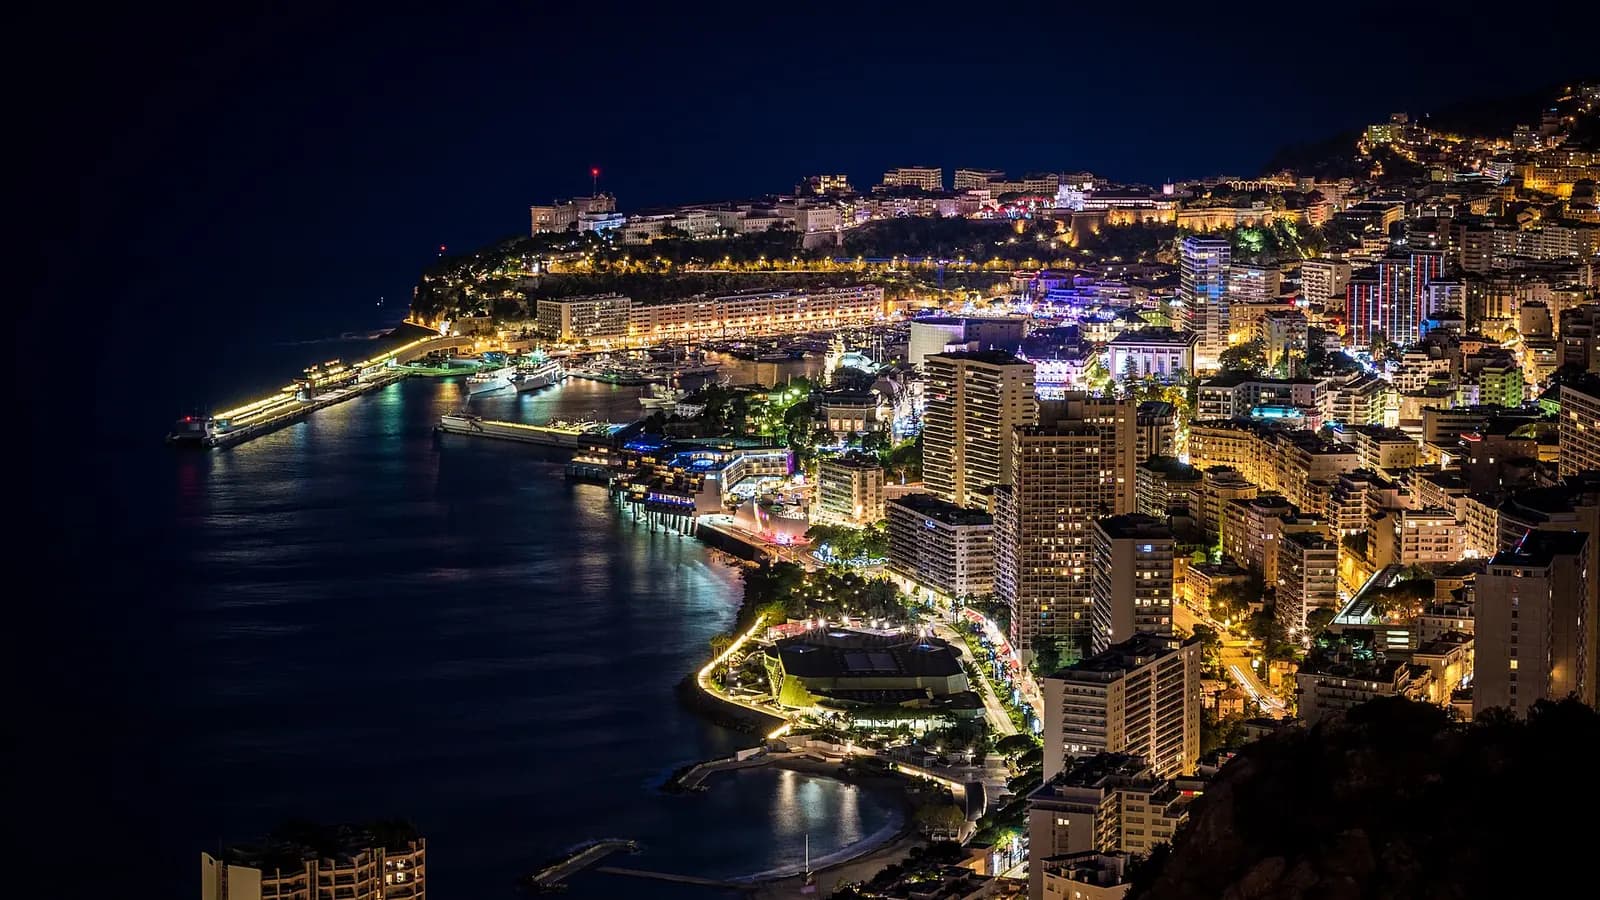
Monaco occupies a singular place in the imagination of internationally mobile wealth. It is small, intensely regulated, and expensive to live in, yet it remains one of the very few European jurisdictions with no personal income tax for most residents. For founders, family offices and private investors weighing where to base a business and a life, the Principality is rarely a casual choice. It is a deliberate one.
The mistake we see most often is treating Monaco company formation as a paperwork exercise that delivers a tax-free trading vehicle. It does not work that way. Monaco's appeal is real, but it is tied to genuine physical presence, careful structuring, and a regulatory regime that scrutinises substance and activity closely.
This guide sets out how companies are formed and operated in Monaco, the actual tax position, the residence and substance dimension, banking realities, and the profile of person for whom the Principality is a sound fit.
Entity types and how formation works
The most common operating vehicle is the SARL (société à responsabilité limitée), the Monegasque equivalent of a private limited company, suited to small and medium businesses with a defined group of shareholders. For larger ventures or those expecting outside investment, the SAM (société anonyme monégasque) is the joint-stock company, broadly comparable to a public limited company and subject to more demanding governance.
Sole traders and professionals often operate through registration as a commerçant or via a civil company structure, depending on the activity. Holding and family-asset arrangements may use a SCI (société civile immobilière) for Monegasque real estate, though this carries its own considerations.
Formation in Monaco is not a same-day affair. Every commercial activity requires authorisation from the government, and the authorities review the proposed business, its premises, and the people behind it. You will typically need a genuine local office, evidence of the activity's viability, and clean documentation on the beneficial owners. Minimum capital requirements apply to the SAM and, in practice, the authorities expect to see real commercial intent rather than a shell.
Approval timelines vary with the activity and the completeness of the file. Regulated or sensitive sectors take longer. We always plan on the basis that the government will ask questions, and we prepare the application to answer them in advance.
The tax position
Monaco's headline attraction is that it levies no personal income tax on most residents. French nationals are an important exception under a long-standing bilateral treaty, and that exception is absolute, so French citizens should take advice before assuming any benefit.
At the corporate level the picture is more nuanced than the "tax-free" shorthand suggests. Monaco applies a business profits tax to companies that earn more than a defined proportion of their turnover from activities conducted outside the Principality, and to those deriving income from patents and intellectual property. A genuinely local business serving the Monegasque market may fall outside the charge; an internationally facing company often does not. The rate has been aligned over recent years with broader European norms, and we treat the current rate as a moving figure to confirm at the point of structuring.
There is no general capital gains tax or wealth tax on individuals, and inheritance and gift treatment is favourable for assets passing in the direct line, though rates rise sharply for transfers to unrelated parties. None of this removes the need to consider how other countries will tax you. If you retain ties, assets or days elsewhere, those jurisdictions may still assert a claim regardless of your Monegasque status.
Residence, substance and the reality of presence
Monaco's benefits are inseparable from living there. To obtain and maintain a residence permit (the carte de séjour), an applicant must generally secure accommodation in the Principality, whether owned or rented, demonstrate sufficient financial means, often evidenced by a deposit with a Monegasque bank, and pass a clean background check.
Maintaining residence requires real presence. The authorities expect Monaco to be your genuine home, and renewals look at whether you actually live there. This is the crucial point that catches people out: a Monaco company combined with a Monaco residence card is only valuable if the substance behind both is authentic. Renting a token apartment while living elsewhere is not a strategy; it is an exposure.
For a company, substance means premises, local administration, and decision-making that genuinely occurs in Monaco. Where a structure is internationally facing, we pay close attention to where management and control sit, because other jurisdictions increasingly tax on that basis.
Banking access and practical operations
Monaco hosts a concentrated private-banking sector accustomed to high-net-worth and corporate clients, but account opening is rigorous. Banks conduct thorough due diligence on source of funds and source of wealth, and they expect a coherent explanation of how the company and its owners generate income. A clean, well-documented file moves faster than a complicated one.
Account opening is frequently linked to the residence process, and a banking relationship may be expected as part of demonstrating financial means. We coordinate the corporate, residence and banking workstreams together rather than sequentially, because they reinforce one another and because the same documentation supports all three.
Operating costs are high. Office space, professional fees and the general cost of living in the Principality are among the steepest in Europe. This is not a jurisdiction for cost minimisation; it is one for individuals and businesses where the lifestyle, prestige and tax position justify the expense.
Compliance and ongoing obligations
Monaco maintains a commercial register, requires proper accounting records, and expects companies to file as their form and activity demand. Beneficial ownership information is collected by the authorities, consistent with international standards, and Monaco participates in cross-border information exchange. The era in which a Monegasque structure offered opacity has passed.
Companies subject to the business profits tax must file accordingly, and all entities must keep their authorisation current and notify the authorities of material changes to activity, ownership or management. Anti-money-laundering obligations are taken seriously across the financial sector, which is why front-loaded, honest documentation is so valuable.
Who Monaco genuinely suits
Monaco suits the individual or family that wants to live in the Principality, not merely to be registered there. It is well matched to entrepreneurs who have realised significant wealth, to family offices seeking a stable European base with no personal income tax, and to businesses with a genuine connection to the local or regional market.
It is poorly matched to anyone seeking a low-cost vehicle, anyone unwilling to relocate, and French nationals expecting income-tax relief. For purely international holding or trading activity without real presence, other jurisdictions are usually more efficient and far less expensive.
How HPT helps
We advise on whether Monaco fits your wider plan before any application is filed, then manage formation, the residence pathway, banking introductions and ongoing compliance as a coordinated whole. Our focus is on building structures that withstand scrutiny in Monaco and in every country you remain connected to.
If you are weighing Monaco against the alternatives, we would be glad to discuss your circumstances in confidence.
This is general information, not advice. It describes rules as we understand them at the date of publication, and those rules differ by jurisdiction and change often. Nothing here takes account of your circumstances, and nothing here creates a professional relationship between us. Advice requires a written engagement letter. Before you act, take advice from a qualified professional in the jurisdiction concerned. Read the full disclaimer.
Talk to us
Does this bear on a matter of yours?
A senior adviser can discuss how it applies to your circumstances.
Sheung Wan, Hong Kong and Mayfair, London · Meetings by appointment only


