


UK to Malta Relocation Guide: Tax, Residency and Setup
A UK to Malta relocation guide covering UK departure rules, Maltese non-dom and remittance taxation, residency programmes, banking and family setup.
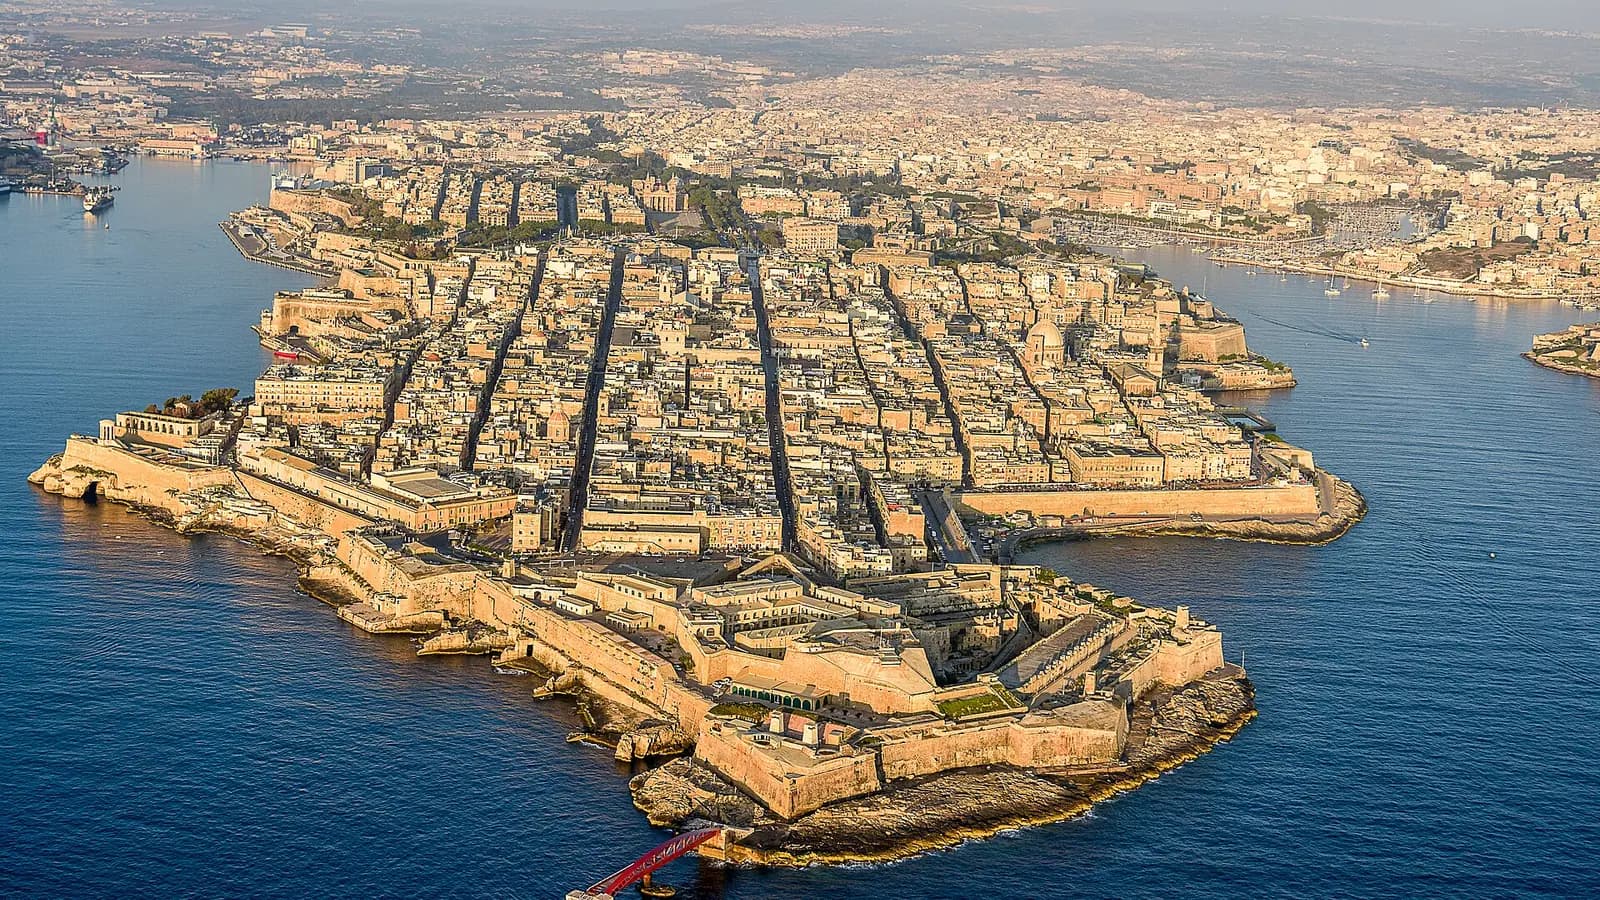
Malta occupies a particular niche for British movers: an English-speaking, EU member state with a common-law heritage, Mediterranean climate, and a tax system built around the remittance principle that feels familiar to anyone who understood the old UK non-dom rules.
For the right person, a UK to Malta relocation combines genuine European residence with a tax position that can be efficient when structured correctly. The phrase "when structured correctly" carries the weight, however. Malta's regime rewards careful planning and punishes the assumption that a Mediterranean island is automatically a tax haven.
This guide covers leaving the UK properly and establishing yourself in Malta in a way that is both efficient and defensible.
Leaving the UK cleanly
UK residence turns on the Statutory Residence Test, which weighs days in the UK against connecting ties such as accommodation, family and work. Becoming non-resident depends on evidenced facts, and split-year treatment may apply to the year of your move where the conditions are met.
Watch the temporary non-residence rules, which can reclaw certain income and gains if you return within roughly five years, so plan a genuine and durable move. UK-source income, notably UK rental profit, generally remains UK-taxable, and UK inheritance tax can still reach you for a period after departure depending on your long-term UK connection. File final returns, fix your departure date in the records, and track UK days afterwards. A clean exit is what lets the Maltese position govern.
The Maltese tax position
Malta's appeal for non-Maltese residents rests on the remittance basis. In broad terms, individuals who are resident but not domiciled in Malta are typically taxed on Maltese-source income and on foreign income remitted to Malta, while foreign income kept outside Malta is generally not taxed there, subject to the detailed rules. Foreign capital gains are, broadly, outside the Maltese net even if remitted, though the position must be checked against current rules and your facts.
This is conceptually familiar to former UK non-doms, but the detail differs and Malta has its own minimum-tax features for certain residence statuses. Several of Malta's residence programmes carry an annual minimum tax contribution, so the regime is rarely zero-tax; it is predictable-tax for those who plan around it. Domicile is a separate and weighty concept: a UK-domiciled individual does not shed UK domicile merely by moving, and that affects UK inheritance tax exposure independently of where you live.
The practical takeaway is to structure how and where you hold and receive income before you arrive, so that remittances are deliberate rather than accidental. Model the outcome under current rules and confirm the minimum-tax obligations attaching to your chosen status.
Residency routes
Since Brexit, Britons are non-EU nationals and need a residence basis. Malta offers several, including ordinary residence for those genuinely living and working there, and dedicated residence programmes aimed at financially independent individuals that require qualifying property (owned or rented) and carry annual minimum-tax commitments. A separate, more rigorous route exists for those seeking citizenship through substantial investment and an extended qualifying period, which is distinct from straightforward residence and subject to strict due diligence.
Choose the route to match your intentions: a residence programme suits many relocators seeking a tax-efficient EU base, while ordinary residence suits those building a genuine working life on the island. As always, a residence status is not automatically a tax-residence outcome; the two must be planned together.
Banking and financial setup
Malta is a small market and its banks are conservative, so account opening can take time and demands thorough documentation: proof of residence, source of wealth, and source of funds. Recent arrivals moving significant sums from the UK should expect detailed enquiry and prepare evidence in advance, business sale records, investment statements, tax returns, and a clear narrative.
Keep your UK banking operational during the transition, and consider that Maltese accounts are reportable to the UK under the Common Reporting Standard while you remain UK resident. Given the remittance basis, the architecture of your accounts, which monies sit where, and which account you remit from, has tax consequences, so set it up deliberately at the outset rather than rearranging it later.
Healthcare, schooling and settling in
Malta operates a public health system accessible to those properly registered, and many residents supplement it with private cover; some residence routes expect proof of health insurance. English is an official language, which eases schooling, healthcare, and daily administration considerably compared with non-English-speaking destinations, a genuine and underrated advantage for families. International schools exist but are limited in number, so apply early. Housing is in demand in the most sought-after areas, and qualifying-property thresholds under residence programmes shape where you can live.
Domicile and the long UK tail
The point that catches more British movers to Malta than any other is domicile. Moving to Malta and even acquiring Maltese residence does not, by itself, change a person's UK domicile of origin. Domicile is a sticky common-law concept tied to your permanent home and intentions over a lifetime, and shedding a UK domicile requires a genuine, evidenced, and lasting severance of UK ties, not merely living abroad.
This matters because UK inheritance tax exposure follows long-term UK connection rather than day-to-day residence. A relocator can be comfortably non-UK-resident for income-tax purposes yet still within the reach of UK inheritance tax on worldwide assets for a considerable period. Any estate planning built around the Malta move should account for this directly, often through the timing of the move, the structuring of assets, and a realistic view of when, if ever, the UK tail falls away.
Account architecture under the remittance basis
Because the Maltese regime turns on what is remitted to Malta, the design of your banking is itself a planning decision. The common approach is to separate accounts by character, keeping clean capital that predates Maltese residence apart from foreign income and gains arising afterwards, so that what you bring into Malta to live on can be drawn from the most tax-efficient pool deliberately rather than by accident.
Get this wrong, mix income and capital in a single account, then remit from it, and you can taint the whole balance and import an avoidable tax charge. Setting up the right account structure before you arrive, and disciplining how you fund Maltese spending thereafter, is one of the highest-value things a new resident can do.
Common pitfalls
The recurring errors: assuming Malta is tax-free rather than remittance-based and minimum-taxed; remitting funds carelessly and creating an avoidable Maltese tax charge; conflating residence status with tax residency; overlooking that UK domicile and the associated UK inheritance tax exposure survive the move; spending too many days in the UK and failing the residence test; and underestimating bank-onboarding timelines. Each is avoidable with planning.
How HPT helps
We run UK to Malta relocations as one coordinated plan: advising on a clean UK exit and split-year position, structuring your income and account architecture around the Maltese remittance basis, selecting the residence route that fits your goals and its minimum-tax commitments, and supporting banking introductions, healthcare and family setup. We coordinate with your UK adviser so the departure is correctly filed and the position is defensible.
If Malta is on your list, talk to us before you move funds or sign a lease, the structure you set up on day one is the one you live with.
This is general information, not advice. It describes rules as we understand them at the date of publication, and those rules differ by jurisdiction and change often. Nothing here takes account of your circumstances, and nothing here creates a professional relationship between us. Advice requires a written engagement letter. Before you act, take advice from a qualified professional in the jurisdiction concerned. Read the full disclaimer.
Talk to us
Does this bear on a matter of yours?
A senior adviser can discuss how it applies to your circumstances.
Sheung Wan, Hong Kong and Mayfair, London · Meetings by appointment only


